Foreign Portfolio Investment (FPI) provides overseas investors a gateway to India’s growing financial markets. Through this route, foreign investors can purchase listed shares, government securities, bonds and other financial instruments without directly managing a business in the country.
These investments bring foreign capital into Indian markets while allowing overseas investors to participate in their growth. But how are the returns earned from these investments taxed in India?
The applicable rates depend on the nature of income and securities involved. Read ahead to know what is FPI in income tax, tax rules, eligibility and regulatory requirements.
Quick Answer:
Foreign Portfolio Investment (FPI) allows foreign investors to invest in Indian financial markets through shares, bonds and other securities without gaining management control of companies. The article explains how FPI income and capital gains are taxed in India, including applicable tax rates, exemptions, DTAA benefits, eligibility criteria and SEBI registration requirements.
Key Takeaways
- Foreign Portfolio Investments are investments made by foreign investors in Indian securities without direct control over businesses.
- The taxation of FPI income and capital gains is governed by Section 210 of ITA 2025.
- FPI tax rates vary according to income type, investor classification and applicable securities transaction tax conditions.
- FPIs can claim tax benefits under DTAA, subject to applicable documentation.
- SEBI regulates FPI registration through two investor categories.
What Is FPI in Income Tax?
Foreign Portfolio Investment (FPI) refers to investments made by non-resident investors, such as foreign funds, pension funds and institutional investors, in India’s financial markets.
Foreign investors purchase securities such as listed shares, government bonds, corporate debt instruments and other market-linked assets without acquiring direct control over the businesses.
The FPI activities are primarily regulated by the Securities and Exchange Board of India (SEBI) under the SEBI (Foreign Portfolio Investors) Regulations, 2019. The investments are further governed by the Foreign Exchange Management Act (FEMA), 1999, and the Non-Debt Instruments Rules, 2019, administered by the RBI.
Here are some key features of FPIs:
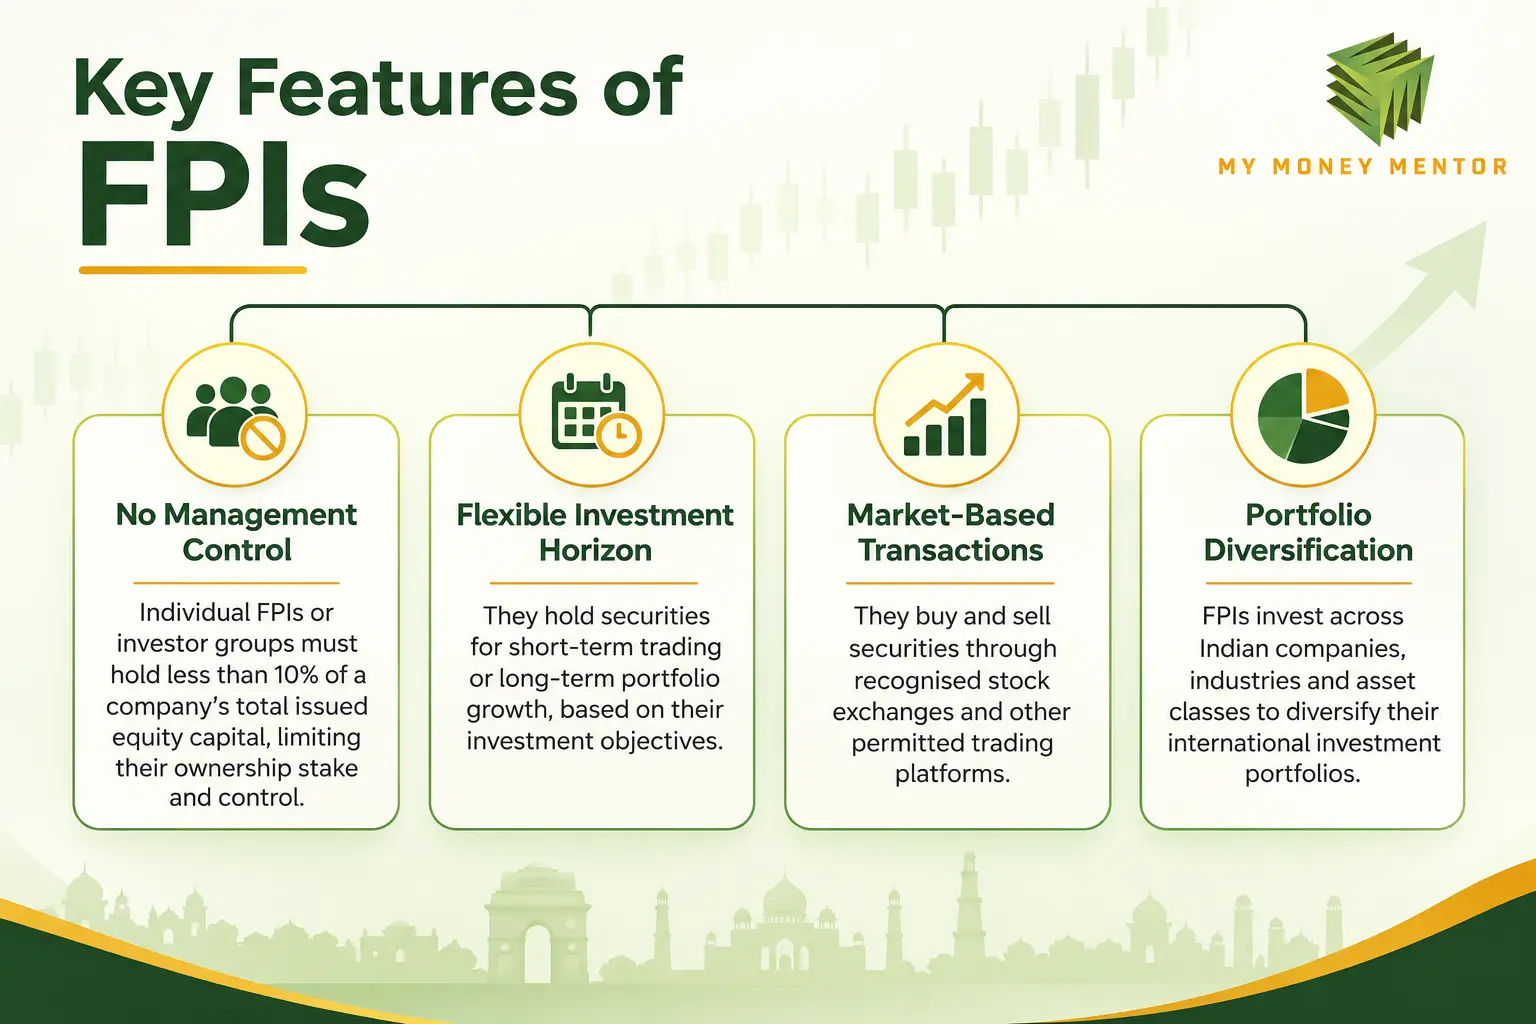
- No management control: Individual FPIs or investor groups must hold less than 10% of a company’s total issued equity capital, limiting their ownership stake and control.
- Flexible investment horizon: They hold securities for short-term trading or long-term portfolio growth, based on their investment objectives.
- Market-based transactions: They buy and sell securities through recognised stock exchanges and other permitted trading platforms.
- Portfolio diversification: FPIs invest across Indian companies, industries and asset classes to diversify their international investment portfolios.
Tax Rules Applicable for FPIs in India
Now that you have understood what is FPI in income tax, let us move into how it is taxed!
Foreign Portfolio Investors (FPIs) referred to as Foreign Institutional Investors (FIIs) under the tax law are subject to a special taxation framework under Section 210 of the Income-tax Act, 2025, which governs income earned from securities and capital gains arising from their transfer.
The provision came into effect on 1 April 2026, replacing Section 115AD of the Income-tax Act, 1961.
Tax Rates on FPI Income and Capital Gains
First, here is a classification of capital gains:
- Short-Term Capital Gains (STCG): The gains from listed securities, Unit Trust of India (UTI) units, equity-oriented fund units and zero-coupon bonds held for 12 months or less. Other capital assets held for 24 months or less also qualify.
- Long-Term Capital Gains (LTCG): The gains from the above securities and assets held for more than 12 months. Other capital assets held for more than 24 months qualify.
The National Stock Exchange (NSE) provides the following rates, effective from 1 April 2026:
- Company and partnership firm FPIs
| Nature of income | Company | Partnership | |||
| Up to ₹1 crore | ₹1–10 crore | Above ₹10 crore | Up to ₹1 crore | Above ₹1 crore | |
| Dividends | 20.800% | 21.216% | 21.840% | 20.800% | 23.296% |
| Income from securities | 20.800% | 21.216% | 21.840% | 20.800% | 23.296% |
| STCG (STT applicable) | 20.800% | 21.216% | 21.840% | 20.800% | 23.296% |
| LTCG (STT applicable) | 13.000% | 13.260% | 13.650% | 13.000% | 14.560% |
| STCG (STT not applicable) | 31.200% | 31.824% | 32.760% | 31.200% | 34.944% |
| LTCG (STT not applicable) | 13.000% | 13.260% | 13.650% | 13.000% | 14.560% |
- FPIs other than companies and partnership firms
| Nature of income | Up to ₹50 lakh | ₹50 lakh–₹1 crore | ₹1–2 crore | ₹2–5 crore | Above ₹5 crore |
| Dividends | 20.800% | 22.880% | 23.920% | 23.920% | 23.920% |
| Income from securities | 20.800% | 22.880% | 23.920% | 26.000% | 28.496% |
| STCG (STT applicable) | 20.800% | 22.880% | 23.920% | 23.920% | 23.920% |
| LTCG (STT applicable) | 13.000% | 14.300% | 14.950% | 14.950% | 14.950% |
| STCG (STT not applicable) | 31.200% | 34.320% | 35.880% | 35.880% | 35.880% |
| LTCG (STT not applicable) | 13.000% | 14.300% | 14.950% | 14.950% | 14.950% |
Note: The rates follow the NSE tax matrix and include applicable surcharge and 4% Health and Education Cess. For LTCG (STT applicable) on listed equity shares, equity-oriented mutual funds, and business trust units, tax applies only to gains exceeding ₹1.25 lakh in a financial year.
Tax Exemptions and Deductions for FPIs
- The interest income and capital gains from Government Securities (G-Secs) are exempt from tax, effective from 1 April 2026.
- FPIs must submit Form 173A under Rule 281A to claim this exemption.
- Section 393 prescribes 20% TDS on securities income covered under Section 210(1). No TDS applies to capital gains covered under Section 210.
- Under Section 159(4), FPIs can apply the provisions of the Double Taxation Avoidance Agreement (DTAA) if they are more beneficial than domestic tax law, subject to holding a valid Tax Residency Certificate (TRC) and furnishing Form 41 as required under Section 159(8) and Rule 75.
- FPIs can further claim credit for Indian taxes paid, including TDS, in their country of residence, subject to the applicable DTAA or domestic tax laws.
- Section 210(4) restricts deductions under Sections 28–58, 60 and 61, Section 93(1)(a) and (e) and Chapter VIII against specified securities income.
- Any specific exemption or concessional tax provision offering more beneficial treatment to an FPI may apply subject to its applicable conditions.
Eligibility and Registration Requirements for FPIs in India
Here are the eligibility criteria an overseas entity must meet to obtain Foreign Portfolio Investor (FPI) registration in India:
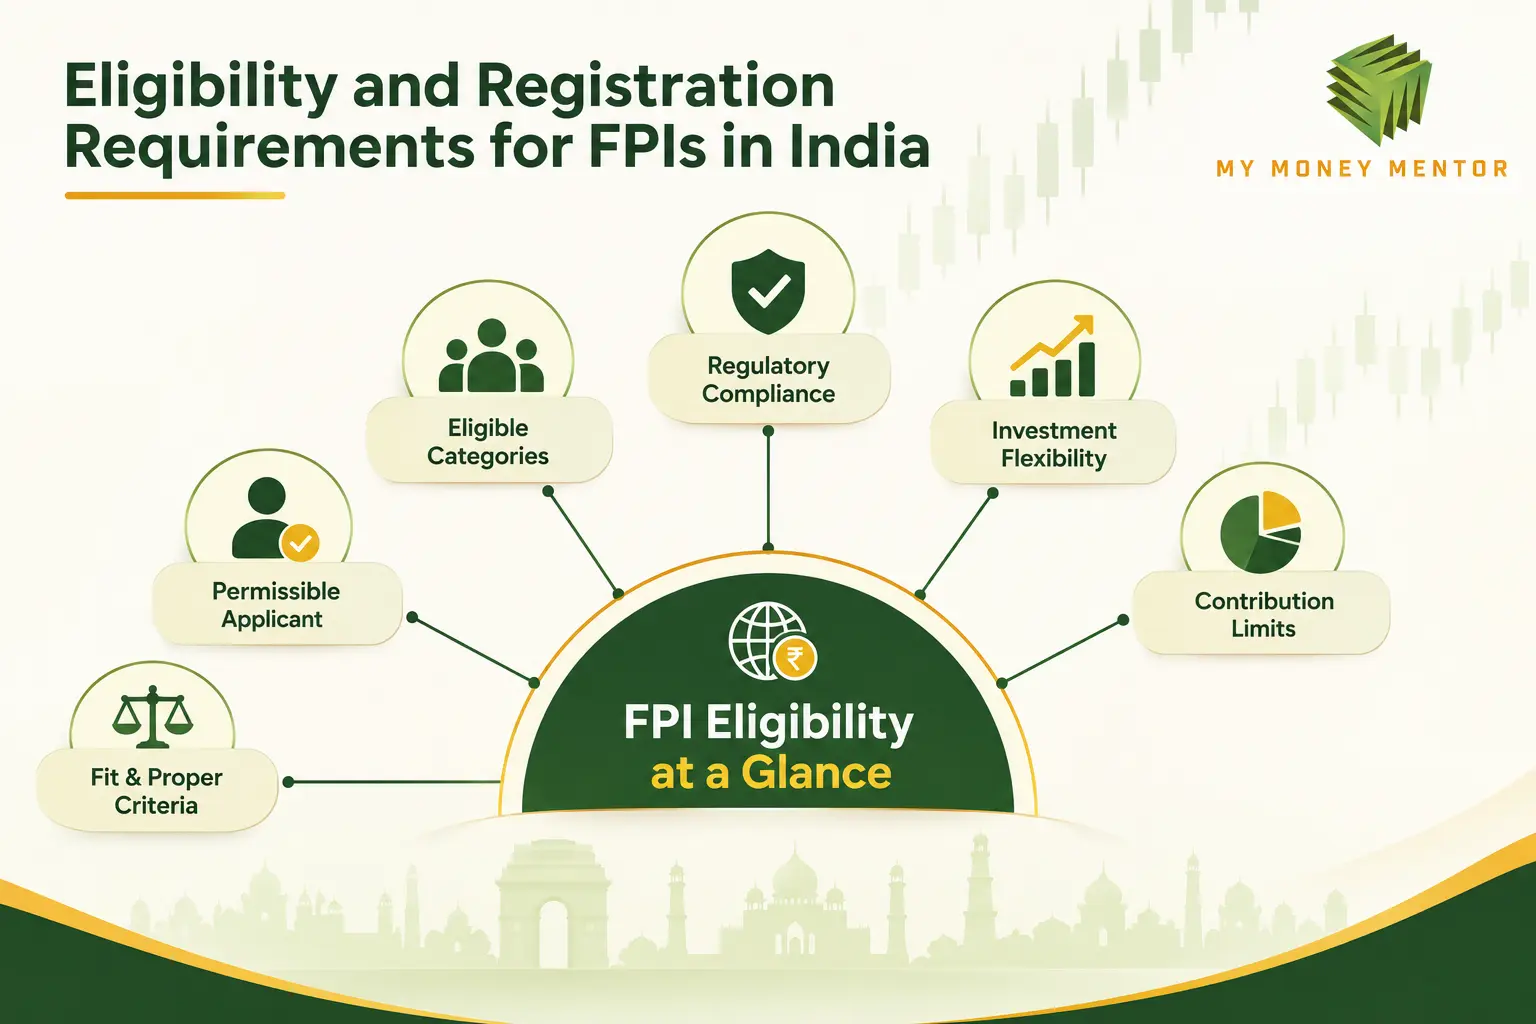
- Registration Categories: The applicants can apply for registration under either of the two categories prescribed by SEBI:
- Category I: Includes government and government-related investors, central banks, sovereign wealth funds, pension funds, university funds and appropriately regulated financial institutions.
- Category II: Includes other investors, such as corporate bodies, individuals, family offices, charitable organisations, endowments, foundations and certain regulated or unregulated funds.
- Applicant Status: The applicant must not be a Resident Indian, Non-Resident Indian or Overseas Citizen of India.
- Contribution Limits: A single Resident Indian, Non-Resident Indian (NRI) or Overseas Citizen of India (OCI) must contribute less than 25% of the Foreign Portfolio Investor’s corpus, and their combined contribution must remain below 50% (except for FPIs based in GIFT City IFSC, where up to 100% aggregate NRI/OCI/RI contribution is permitted subject to SEBI conditions).
- Regulatory Requirements: The applicant must meet the prescribed country, regulatory and supervision requirements under the Securities and Exchange Board of India regulations.
- Investment Eligibility: The applicant must be legally permitted to invest in securities outside its country of incorporation.
- Fit and Proper Criteria: The applicant must maintain a satisfactory track record, financial standing and professional competence.
Conclusion
India’s financial markets offer overseas investors several opportunities. But the tax rules can make a significant difference to their actual returns. From capital gains and dividend taxation to exemptions and treaty benefits, every provision matters when managing an investment portfolio.
Knowing what is FPI in income tax helps you understand what they earn, what they owe and which tax benefits they can claim. Investcon Market Intelligence breaks down these regulations into practical financial insights, helping you to make sense of India’s evolving investment and taxation landscape.
FAQs
Q: What is the difference between FPI and FDI?
Ans: Foreign Portfolio Investment (FPI) is a passive investment of less than 10% in financial assets like stocks or bonds, with no operational control. On the contrary, Foreign Direct Investment (FDI) involves a 10% or more ownership stake, with lasting management control over foreign business assets.
Q: Can FPIs repatriate their investment proceeds outside India?
Ans: Yes. FPIs can repatriate their investment proceeds, including capital gains, dividends, interest, and sale or redemption proceeds, outside India.
Q: Is derivative trading allowed for FPIs in India?
Ans: Yes. FPIs can trade in exchange-traded equity, currency, and interest rate derivative contracts on recognised Indian stock exchanges, subject to position limits and margin requirements prescribed by SEBI and the RBI.
Q: Can FPIs carry forward capital losses in India?
Ans: Yes. The capital losses can be carried forward for up to eight tax years, subject to timely return filing and applicable set-off conditions.
Q: Can FPIs invest in unlisted Indian companies?
Ans: No, Foreign Portfolio Investors (FPIs) are not permitted to invest in unlisted equity shares of Indian companies strictly through the FPI route.
Juri is a finance writer, experienced in developing content across financial markets and investments. She holds an MBA in Finance and writes about the stock market, mutual funds, IPOs, personal finance and market developments. Her work focuses on producing researched and informative content that makes financial topics accessible and relevant to readers.